Your right under federal law (FCRA §611) — not a loophole, not a trick
Errors on your credit report aren't permanent.
1 in 5 credit reports has an error (FTC study). Upload yours — DisputeKit finds what's disputable and writes the formal letters that make bureaus fix it. In plain English. In minutes.
🔒
SSN auto-removed
Your Social Security number is stripped out before analysis.
🗑️
Nothing stored
No accounts, no databases. Close the tab and it's gone.
⚖️
Your legal right
Disputing errors is free under the Fair Credit Reporting Act.
📉
Never hurts your score
Checking your own report is a soft pull. Disputing is free.
A single error can cost you thousands.
A wrong late payment. A collection that isn't yours. A debt from 8 years ago that should have aged off. These aren't rare glitches — and they quietly decide whether you get the apartment, the car loan, or the job.
- ✓Denied applications — landlords and lenders pull your report first.
- ✓Higher interest rates — even 1% more on a car loan is thousands over the term.
- ✓It's not your fault — bureaus process billions of data points; mistakes are routine.
1 in 5
consumers had an error on at least one of their credit reports, in an FTC study of the U.S. credit reporting industry.
And the bureaus won't find those errors for you. The law puts the power in your hands — if you know how to use it.
From confused to mailed in 15 minutes
No legal knowledge needed. No staring at a 40-page PDF wondering what any of it means.
Step 1
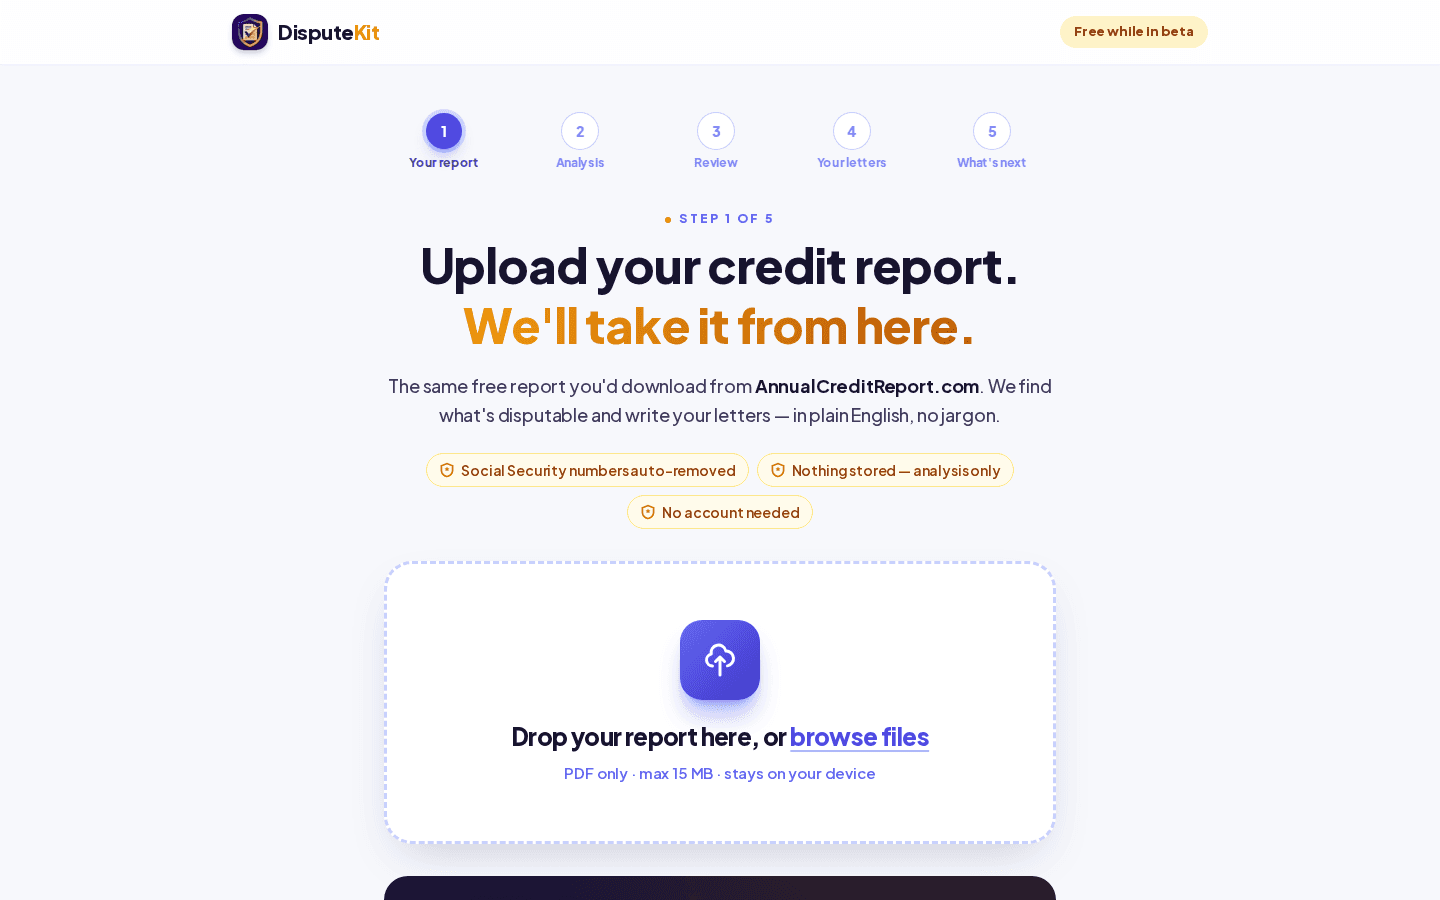
Upload your report
The free PDF from AnnualCreditReport.com. We automatically remove your Social Security number before anything is analyzed — privacy isn't a setting here, it's the default.
Step 2
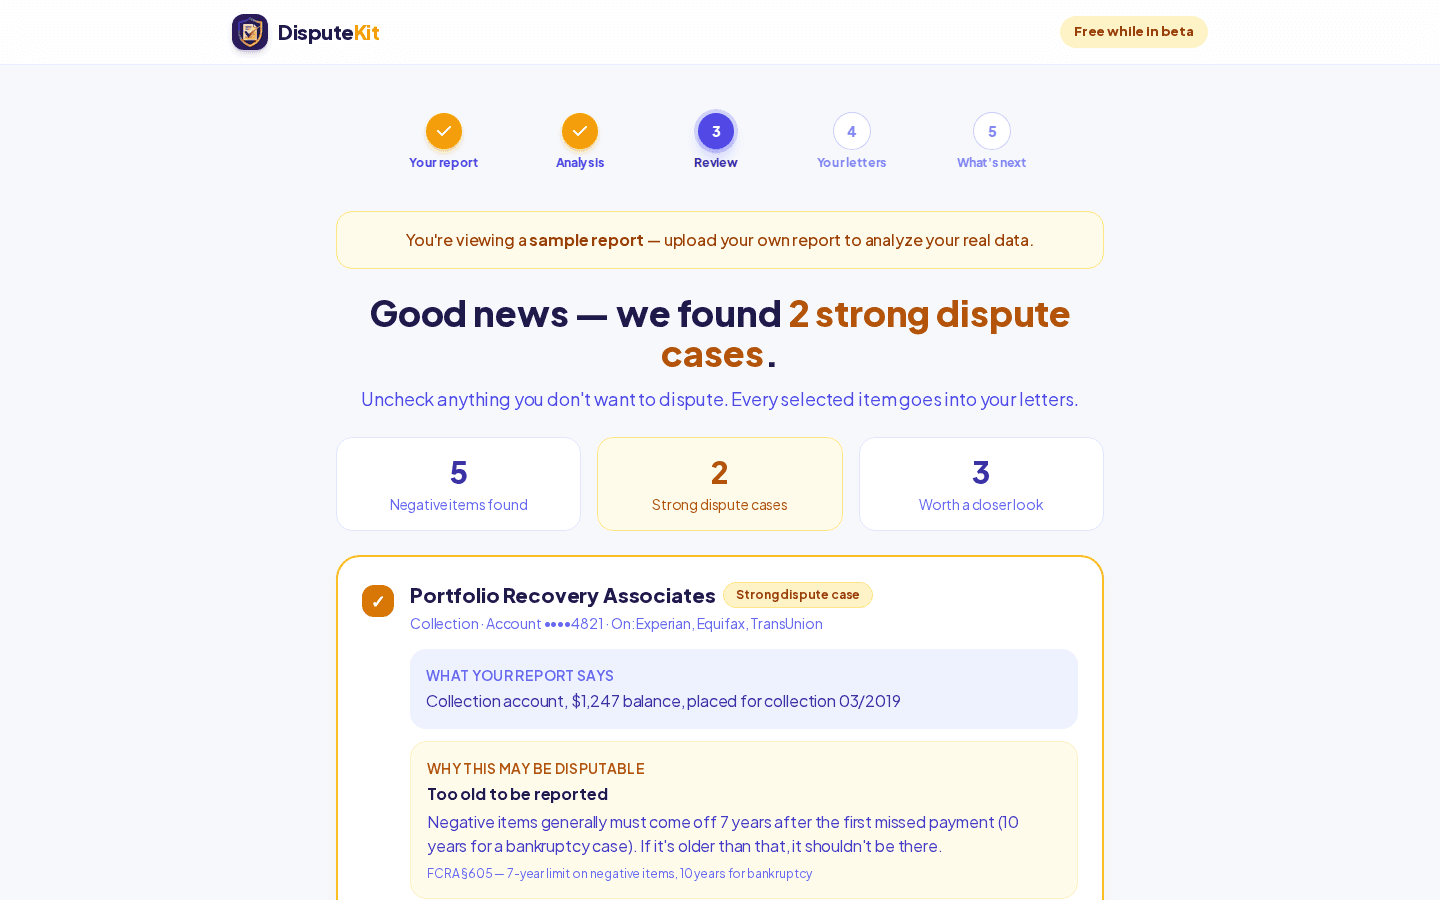
See exactly what's wrong — in plain English
Every negative item explained like a friend would explain it: what the report says, why it may be disputable, and the law behind it. You stay in control — uncheck anything you don't want to dispute.
Step 3
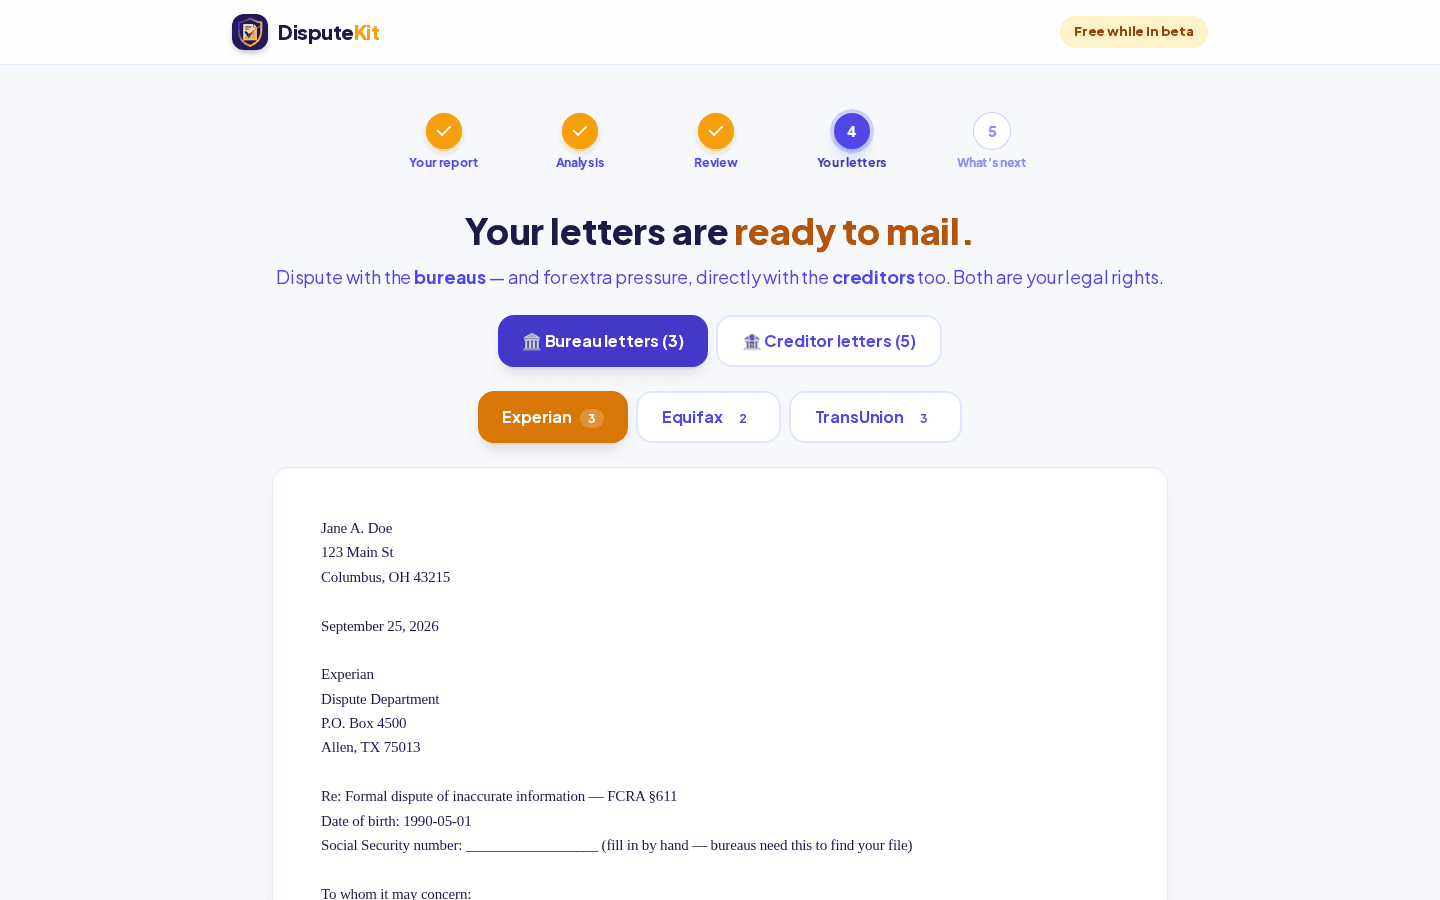
Mail letters that bureaus must answer
Formal dispute letters for Experian, Equifax, and TransUnion — plus direct dispute letters to the creditors themselves for double pressure. Print, sign, send certified mail. By law, bureaus must investigate within 30 days.
Everything included. Nothing upsold.
🏛️
Bureau dispute letters
Formal FCRA §611 letters for Experian, Equifax, and TransUnion with the verified mailing addresses.
🏦
Creditor dispute letters
Direct disputes to the companies that reported you (FCRA §623) — the second front most people never use.
🔁
Round-two toolkit
If a bureau 'verifies' anyway, generate a Method-of-Verification letter demanding they show their work.
📅
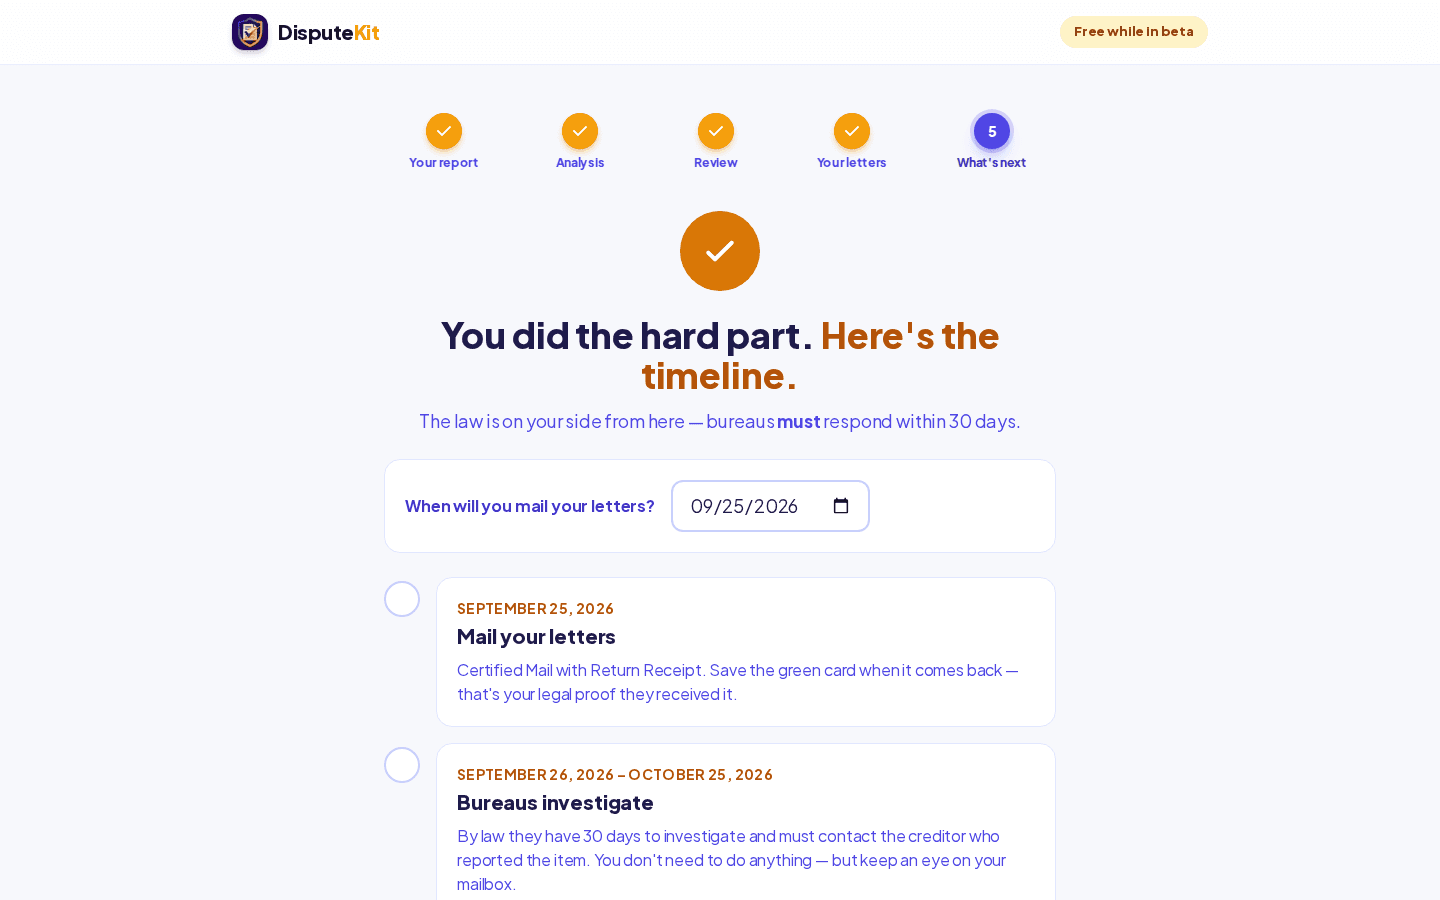
30-day tracker
A personal timeline from mailing day to the legal response deadline, with checkable steps.
🏛️
CFPB escalation path
Still stuck? One click to the official Consumer Financial Protection Bureau complaint portal.
🔒
Privacy by design
SSN auto-redaction, no accounts, no storage, no selling data. Ever.
We're not a "credit repair company." That's the point.
Credit repair companies charge monthly fees and make big promises. We do the opposite:
No monthly fees
One simple tool. No subscriptions, no $99/month 'programs'.
No false promises
We never guarantee score increases or removals. Anyone who does is lying to you.
You stay in control
You review every item, sign every letter, and mail them yourself. Nothing happens without you.
DisputeKit is an educational tool. We're not a law firm and this isn't legal advice — it's your own federally protected right, made easy.
Questions everyone asks
Will disputing hurt my credit score?+
No. Filing a dispute never lowers your score, and checking your own report is a 'soft' inquiry that's invisible to lenders. The only thing that changes your score is the outcome — corrected errors can only help.
Is this really free? What's the catch?+
Analyzing your report and generating your letters is free while we're in beta. There's no account, no credit card, and no subscription. If we ever charge, it will be a simple one-time price — never a monthly fee.
How is this different from asking ChatGPT?+
ChatGPT can show you your report, but it can't prepare your case: item-by-item analysis with FCRA reasoning, formal letters to all three bureaus plus the creditors, a round-two verification toolkit, and a 30-day legal timeline. That's what DisputeKit does.
Is my personal data safe?+
Your Social Security number is automatically removed before analysis. We have no user accounts and no database — your report and your details exist only in your browser tab and vanish when you close it.
How long does the process take?+
Your letters take about 15 minutes to prepare. By law, bureaus must complete their investigation within 30 days of receiving your dispute (up to 45 if you send follow-up information).
What if the bureau says the item was 'verified'?+
That happens — and it's not the end. The toolkit includes a Method-of-Verification letter (they must explain how they verified within 15 days), direct creditor disputes, and the free CFPB complaint process.
Do you guarantee my score will go up?+
No — and run from anyone who does. What we guarantee is a correct, complete, professional dispute package that exercises your full rights under the law.
Your report might be wrong. Find out in 5 minutes.
Free analysis. Real letters. Your legal right. The only thing standing between you and a cleaner report is 15 minutes.
Analyze my report — free →No account · No credit card · Nothing stored